Buying an open plot is an important financial decision for anyone planning to build a dream home or invest in real estate. However, many buyers have one common question: Can you buy an open plot with a home loan?
The answer is yes, in many cases. Banks and housing finance companies in India offer loans for eligible residential plots. Depending on the lender, you may be able to apply for a plot loan, land loan, or plot-plus-construction loan.
However, these loan options have different eligibility criteria, repayment conditions, and property requirements. Before applying, it is important to understand the differences, check your financial eligibility, and verify the legal status of the plot.
In this guide, we explain how to finance an open plot, what documents you need, how lenders assess applications, and what you should check before buying residential land in Hyderabad or elsewhere in India.
Focus keyword: can you buy an open plot with a home loan
Table of Contents
Can You Buy an Open Plot With a Home Loan in India?
Yes, you may be able to finance an eligible residential plot through a bank or housing finance company. However, lenders often offer a specific plot loan rather than a conventional home loan used to purchase a completed house or apartment.
Some lenders also offer combined financing for purchasing a plot and constructing a house. The available options depend on the property, the borrower’s income, and the lender’s current policies.
Before applying, check the official loan information published by ICICI Bank and HDFC Bank. Compare their current eligibility requirements and terms rather than assuming all lenders offer the same conditions.
<IMAGE 1: Insert a landscape photograph of residential open plots with internal roads and greenery near Hyderabad.>
Image alt text: Residential open plots in Hyderabad for buyers considering a plot loan.
What Types of Loans Are Available for Buying an Open Plot?
Understanding the available loan options can help you select a financing arrangement that matches your plans.
1. Residential Plot Loan
A residential plot loan is intended to help eligible buyers purchase land for residential purposes.
Depending on the lender, the property may need to be in an approved layout and within an acceptable location. The lender may also require proof of clear ownership and other legal documents.
A plot loan may be suitable if you want to purchase land first and construct a home later, provided you comply with the loan agreement.
2. Plot-Plus-Construction Loan
A plot-plus-construction loan combines financing for purchasing a residential plot and building a house.
This option may suit buyers who are ready to plan construction. The lender may ask for an approved building plan, construction estimate, and supporting documents before releasing the relevant funds.
Review the lender’s terms carefully. For an example of a combined plot and construction financing product, visit ICICI Home Finance.
<IMAGE 2: Insert an illustration or photograph showing a residential plot beside a completed modern house, representing plot purchase and home construction.>
Image alt text: Residential plot and house construction for buyers comparing plot loan options.
3. Home Construction Loan
If you already own a suitable residential plot, you may be able to apply for a home construction loan to build a house.
The lender may evaluate your income, construction estimate, building permissions, property documents, and repayment capacity.
You should confirm the specific requirements with the lender before starting construction.
Difference Between a Plot Loan and a Home Loan
Although these loans are related, their purposes can differ.
| Feature | Plot Loan | Conventional Home Loan |
|---|---|---|
| Main purpose | Purchase eligible residential land | Purchase or construct a residential house |
| Property | Eligible residential plot | Eligible house or apartment |
| Construction conditions | May apply under the loan agreement | Depend on the loan purpose |
| Loan amount | Based on lender criteria and eligibility | Based on lender criteria and eligibility |
| Tax treatment | Plot purchase alone generally does not qualify for home-loan tax benefits | Eligible housing-loan benefits may apply subject to tax rules |
These are general distinctions. Read the applicable loan agreement and consult a qualified tax professional if you need advice about deductions.
Who Is Eligible for an Open Plot Loan?
Lenders assess several factors before approving a plot loan.
Age and Income
Applicants must meet the lender’s age, income, and repayment requirements. Salaried employees and self-employed applicants may qualify under the relevant product criteria.
Credit History
Your credit history and existing financial obligations can influence the lender’s decision. Check your credit report and correct any errors before submitting an application.
Employment and Financial Stability
Lenders may review salary slips, bank statements, income tax returns, or business financial statements, depending on your employment type.
Property Eligibility
The proposed plot must satisfy the lender’s legal and technical requirements. These may include approved layout status, acceptable land use, ownership documents, and location restrictions.
Meeting the income criteria does not guarantee approval if the property fails the lender’s checks.
How Much Loan Can You Get for an Open Plot?
The loan amount depends on the lender’s policy, the eligible property value, your income, credit profile, and other financial commitments.
For example, consider a hypothetical residential plot costing ₹20 lakh.
- Plot price: ₹20,00,000
- Illustrative financing at 70%: ₹14,00,000
- Your contribution toward the plot price: ₹6,00,000
This is only a mathematical example, not a claim about the percentage any particular bank will finance. Your actual contribution could be higher.
You should also budget for stamp duty, registration charges, legal verification, processing fees, and other applicable expenses.
To estimate your monthly repayments, check the relevant lender’s current loan information and ask for a repayment schedule before committing.
Documents Required for an Open Plot Loan
Prepare the following documents, subject to the lender’s requirements.
Personal and Income Documents
- Identity and address proof.
- PAN and applicable KYC documents.
- Salary slips or other income proof.
- Bank statements.
- Income tax returns or business financial statements, where applicable.
- Details of existing loans.
Property Documents
- Sale deed and relevant title documents.
- Previous ownership records.
- Encumbrance Certificate for the relevant period.
- Approved layout plan and applicable permissions.
- Plot number, survey number, and boundary details.
- Draft sale agreement and seller documents.
- Other documents requested by the lender.
For plots in Hyderabad and surrounding areas, verify the relevant planning authority and applicable permissions. Visit the official Hyderabad Metropolitan Development Authority (HMDA) website for planning information.
You can also use the Telangana RERA official portal to look for relevant registered project information where applicable.
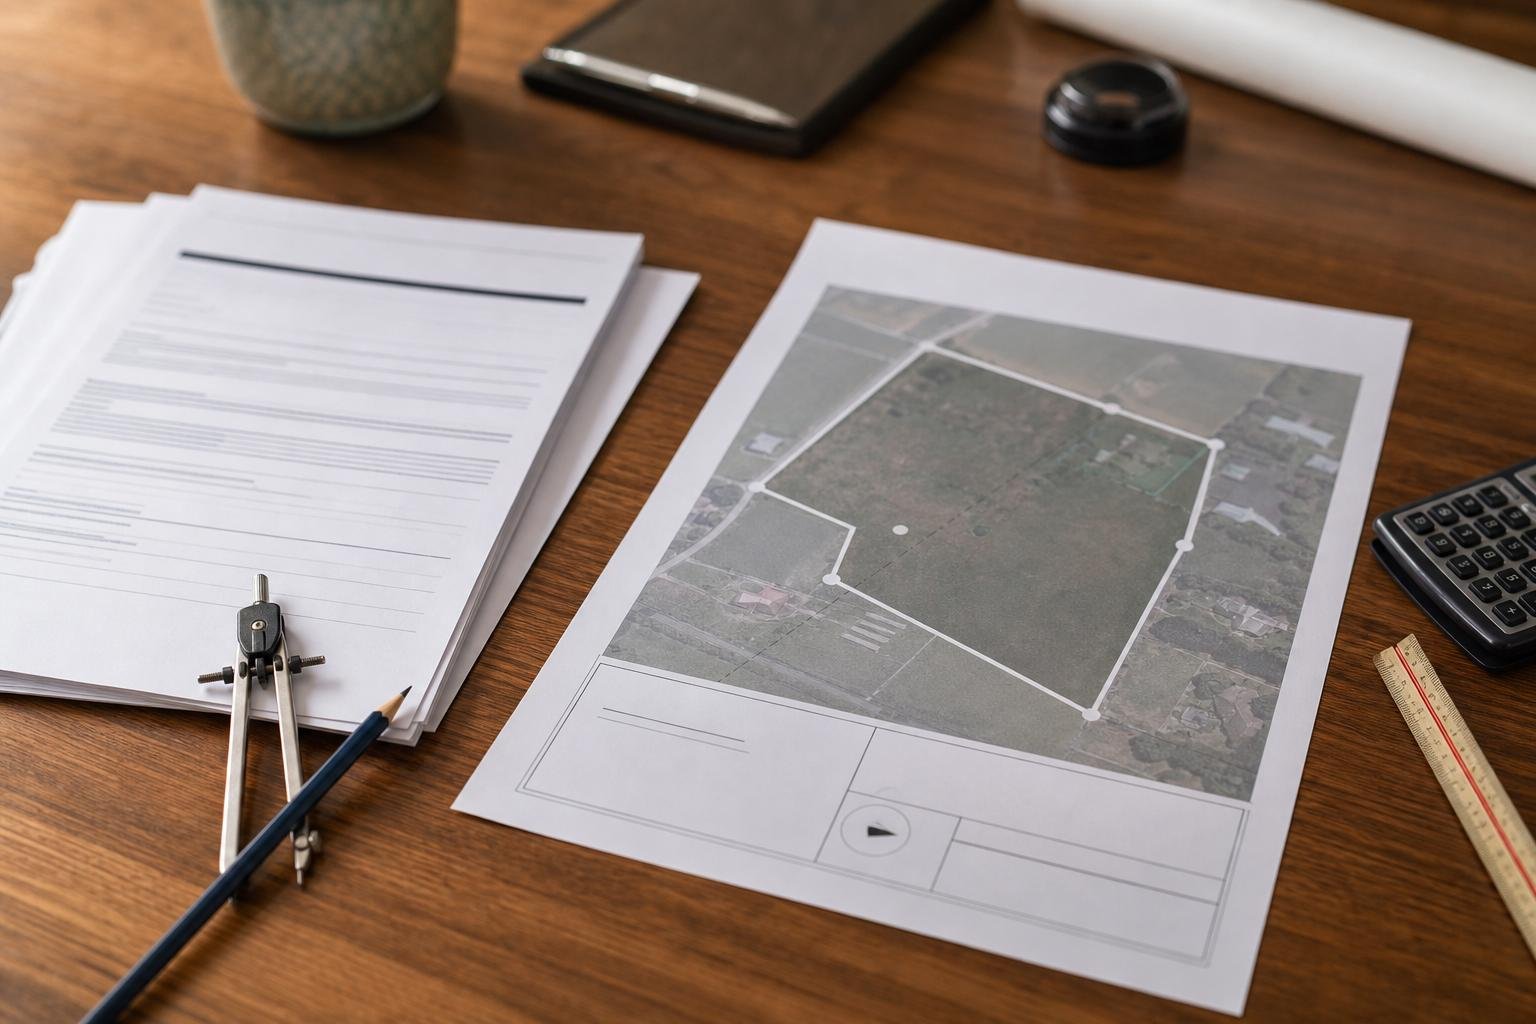
An approval certificate or Encumbrance Certificate alone does not guarantee clear ownership. Consider having a qualified property lawyer review the documents before paying a substantial advance.
<IMAGE 3: Insert a professional photograph of property documents, a land survey map, and a pen on a desk. Do not show real personal information.>
Image alt text: Property documents and land records to check before applying for an open plot loan.
How to Apply for an Open Plot Loan
Follow these steps to start your application.
Step 1: Select a Suitable Plot
Choose a plot that fits your budget and intended use. Check its location, road access, surrounding infrastructure, and legal documentation.
Step 2: Compare Lenders
Compare plot loan and plot-plus-construction loan products. Review interest rates, processing fees, repayment tenure, prepayment conditions, and construction requirements.
Start with the official ICICI Bank Land Loan information and HDFC Bank Plot Loans page.
Step 3: Check Your Eligibility
Use the lender’s eligibility calculator, if available, or contact its loan representative. Estimate the monthly repayment and account for your other expenses.
Step 4: Submit Your Application
Complete the application and submit the required income, identity, and property documents. The lender may conduct legal and technical checks before making a decision.
Step 5: Review the Sanction Letter
If approved, read the sanction letter carefully. Check the interest rate, loan amount, repayment schedule, applicable fees, and any construction deadline.
Step 6: Complete the Purchase
Follow the lender’s disbursement instructions and complete the applicable property registration formalities. Keep copies of all agreements, receipts, and important records.
Important Things to Check Before Taking a Plot Loan
Construction Deadline
Some plot loan products impose a construction deadline. Confirm whether you must build a house within a specified period and what happens if you do not meet the condition.
Interest Rate and Fees
Compare the total borrowing cost, including applicable fees and charges. Do not select a loan based only on its advertised interest rate.
Legal Approval and Ownership
Verify the seller’s ownership, land use, plot boundaries, and applicable layout approvals. Check the relevant official authority rather than relying only on marketing materials.
Monthly Repayment Capacity
Choose a loan amount that leaves enough room for regular household expenses, emergencies, and future construction costs.
Tax Benefits
A plot purchase alone does not automatically qualify for the same tax benefits as a qualifying home loan. Tax treatment depends on the circumstances and applicable tax provisions.
Consult a qualified tax professional before relying on any expected deduction.
Frequently Asked Questions
1. Can I get a home loan to buy only an open plot?
You may qualify for a residential plot loan if you and the property meet the lender’s criteria. Ask specifically about plot purchase financing.
2. Can I buy an open plot without constructing a house immediately?
Possibly. However, some lenders impose construction conditions or deadlines. Check the exact terms before applying.
3. Can I get a loan for an HMDA-approved plot?
A plot in an eligible, properly approved layout may be considered by a lender. HMDA approval alone does not guarantee loan approval.
4. Can self-employed people apply for a plot loan?
Some lenders accept applications from self-employed individuals. They may request income tax returns, bank statements, business records, and other supporting documents.
5. Can I get a loan for an agricultural plot?
Do not assume that agricultural land qualifies for a residential plot loan. The land classification, intended use, applicable laws, and lender’s policy must be checked.
6. Is a plot loan better than a plot-plus-construction loan?
It depends on your plans. A plot loan may suit a separate land purchase, while a combined loan may suit buyers planning to purchase land and build a home.
Conclusion
Buying an open plot with financing is possible in India when the borrower and property satisfy the lender’s requirements. Residential plot loans, plot-plus-construction loans, and construction loans serve different purposes.
Before making a decision, compare lenders, verify property documents, assess your repayment capacity, and understand any construction conditions. If you are planning to buy land in Hyderabad or elsewhere in Telangana, careful research can help you avoid costly mistakes.
For more information about plot buying, land verification, and real estate investment, explore DigitalPlots.site.
Disclaimer: This article is for general educational purposes and does not constitute financial, legal, or tax advice. Loan terms and eligibility requirements can change. Confirm current conditions with the lender and consult qualified professionals before making a financial commitment.